 Field notes ·
Alpine Gold and UPMA: How the Precious Metals Account and Trust Work
Alpine Gold offers an online account for buying, holding, transferring, and withdrawing precious metals, including gold, silver, and Goldbacks. UPMA’s current bylaws describe a personal member trust for eligible metal holdings. Here is what that structure means, what the provider says it costs, and what to check before committing money.
Affiliate disclosure
This article contains an affiliate link. If you sign up or make qualifying purchases through it, ForgeMesh may earn a commission. This does not change the importance of checking the provider’s current prices and terms yourself. Visit Alpine Gold’s account portal.
Who does what—and what is the trust?
Alpine Gold Exchange markets account and vaulting services. UPMA describes itself as a cooperative association. Its 2026 bylaws say members place eligible gold or silver currency into a personal member trust maintained by Legal Tender Services (LTS) or another law firm selected by its board; UPMA says it is not the trustee. UPMA’s description of its relationship with LTS says LTS provides trust and escrow services.
Alpine advertises free account creation, and UPMA describes free Goldback accounts. That does not mean all holdings and transactions are free. Ask for the current trust agreement and fee schedule before signing. A provider’s account trust is not automatically a comprehensive living trust for your home, other assets, or estate; its scope and any tax or estate effects depend on the documents and your circumstances. An independent estate attorney can explain them.
What you can hold and do
Alpine says members can buy, sell and transfer eligible metals, view account statements, request physical withdrawal for pickup or shipment, and designate beneficiaries who have their own account. Its FAQ describes these services and conditions. Verify the exact form of metal, delivery availability, shipping costs, and account rights before purchasing.
Goldbacks are a separate product from a bullion coin or bar. Compare the price per actual troy ounce of gold, any product premium, and the price you would receive on resale. Goldbacks’ usefulness for purchases also depends on finding a willing merchant.
What it costs: examples, not quotes
As of November 5, 2026, Alpine’s rates and fees list Goldback account vaulting at no cost; other holdings carry monthly vaulting charges. Its published example for a $10,000 vaulted silver account is $5 per month. If that value and fee stayed constant for 12 months, that would be about $60, excluding any price changes and other charges; fees are deducted in metal.
The same schedule lists incoming wires at $15, outgoing domestic wires at $30, Stripe ACH deposits at 1% capped at $10, and card transactions at 3.5%. Other bank, withdrawal, shipping, or special-request costs may apply. For example, a $1,000 card transaction at 3.5% implies a $35 fee before any other costs, if that fee applies to the transaction.
Alpine advertises a 0% spread on eligible liquidations when deposit rewards are applied, subject to a weekly limit, daily availability, and other terms. Liquidations beyond eligible rewards use the standard market spread. Request the current purchase and buyback quotes for the same item and amount; a zero-spread offer under specific conditions does not mean every purchase and sale is cost-free.
Potential benefits—and real tradeoffs
Precious metals can provide a different kind of exposure from stocks or cash and may help diversify some portfolios. Physical holdings can also be withdrawn if the provider’s terms and inventory permit. But gold and silver prices can fall, do not guarantee protection from inflation, and typically do not produce cash flow on their own. Premiums, spreads, storage, insurance, and shipping can reduce returns. The CFTC’s guide recommends comparing the metal’s spot value with the retail price and asking what the dealer would pay to buy it back.
Alpine says stored metals are insured against physical loss, theft, and damage. Ask for the actual policy, exclusions, limits, and claims process. Insurance against physical loss does not protect against a fall in the market price. Ask who holds title and what happens if the custodian or service provider fails; do not assume bank deposit insurance applies to the metal.
Alpine also offers optional metal leases. Its fee schedule lists a 60-day cancellation notice and a 3% early-release fee; the provider says leased balances have no vaulting fee. Leasing adds counterparty and liquidity risks, so read the actual agreement and verify how metal or its value would be returned before participating.
Questions to ask before opening or funding
Ask Alpine for the trust agreement and identify the trustee, beneficiaries, assets covered, powers, termination and any legal fees. Confirm whether the account meets your estate-planning needs with an independent attorney.
Ask for an itemized quote for the metal, the same-day buyback quote, the complete current fee schedule, withdrawal and delivery costs, and any restrictions on holding or selling. If considering a lease, ask about counterparty default, insurance and withdrawal timing.
You can review Alpine Gold’s account portal through our affiliate link. ForgeMesh may receive a commission for qualifying activity. This article is general information, not personalized financial, legal, or tax advice. Terms and rates can change.
- precious-metals
- gold
- financial-education
- trusts
 Dub Town is open. Give your website a little place in it.
 Coinbase’s x402 Bazaar Count Fell From 106,068 to 28,135. What Happened?
 That "Security Researcher" Email Is Just a Free Scan. Run It Yourself.
 We Moved Into Square Town. Please Kiss Our Favicon.
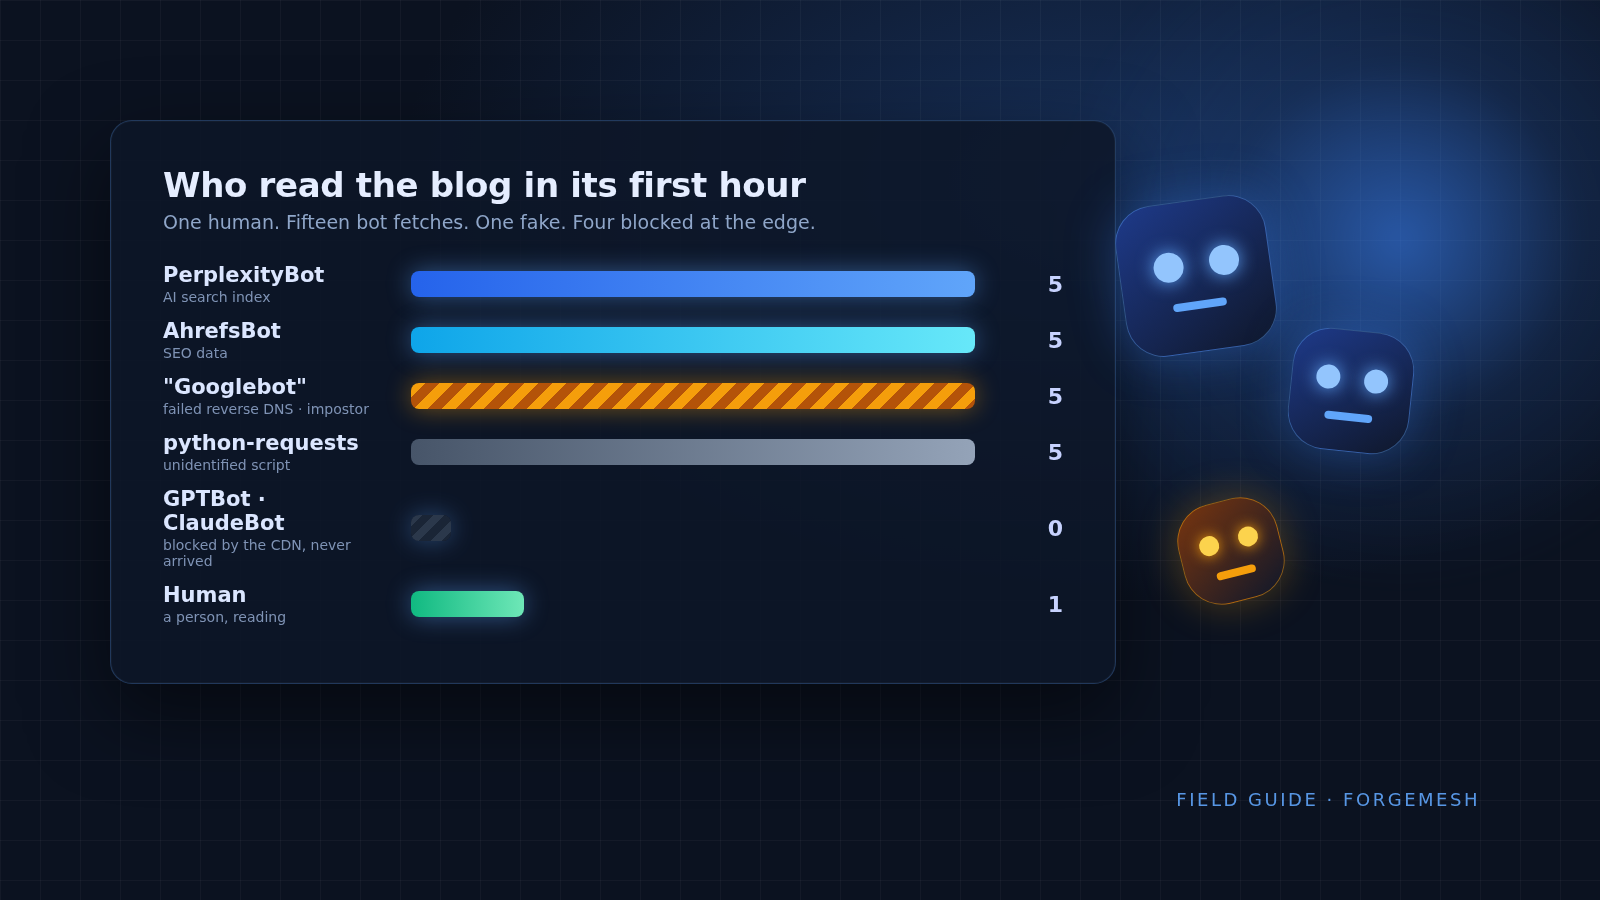 The bots that read your website, and what each one wants
 The agent gateway scramble: who lets shopping agents in, who locks them out, and who charges at the door